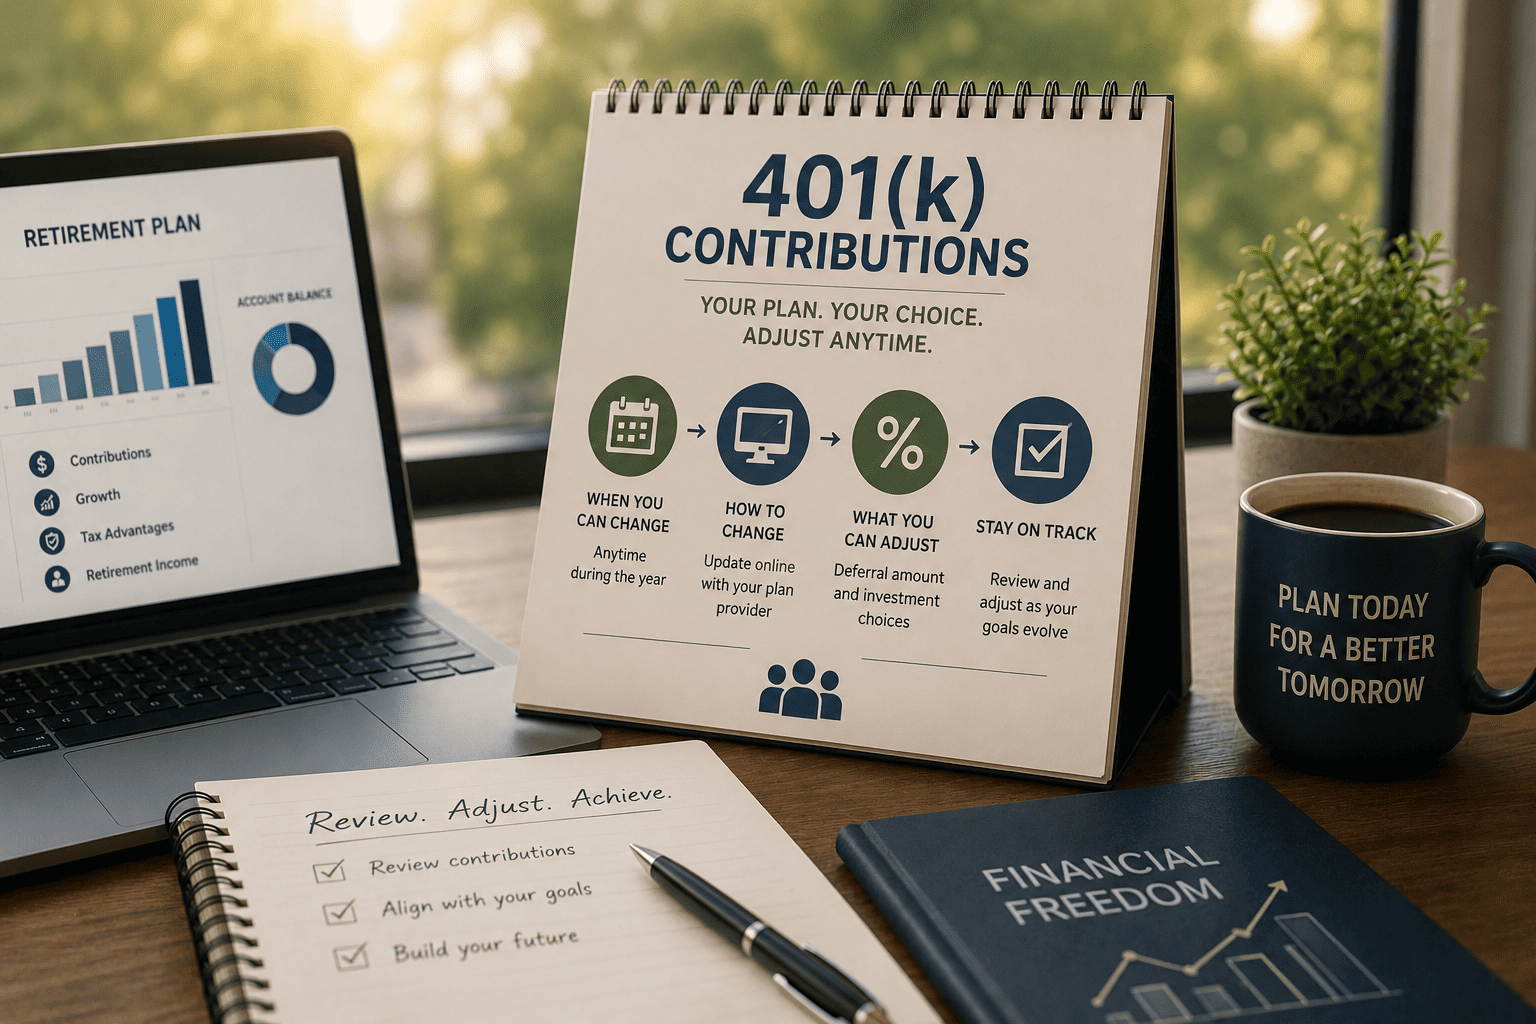
A 401(k) contribution rate is not necessarily fixed for the entire time an employee participates in a plan. Depending on the terms of the employer-sponsored plan, participants may be able to increase, decrease, or otherwise change the amount they contribute from their paycheck.
The timing and process for making a change depend on the specific plan. Some plans may allow changes through an online benefits portal, while others may require a form or another process established by the plan administrator.
Key Takeaways!
Not necessarily.
Whether and how frequently a participant can change a 401(k) contribution generally depends on the terms of the employer’s plan.
The plan may specify when contribution elections can be changed and when a new election becomes effective. The process may also differ between employers.
For example, a plan may provide an online system where participants can update their contribution percentage. Another plan may require a form or other administrative procedure.
Because these rules are plan-specific, participants should check their plan’s summary plan description, benefits portal, or plan administrator for the applicable requirements.
The exact process varies by employer, but a contribution change commonly involves the following steps.
Start by checking the plan documents or employee benefits portal.
Look for information about:
The plan’s terms are important because federal contribution limits do not necessarily describe every operational rule of an individual plan.
Many employers provide an online benefits platform or retirement-plan website where participants can manage contribution elections.
Depending on the plan, participants may be asked to:
If an online option is not available, the plan administrator can explain the applicable process.
A contribution election may not take effect immediately.
The plan may establish a cutoff date or specify the payroll period when a new election becomes effective. After submitting a change, participants can check their confirmation information or contact the plan administrator to determine when the new amount should appear in payroll deductions.
After the change becomes effective, reviewing a subsequent paycheck can help confirm that the contribution election was processed as expected.
Participants can also compare the payroll deduction with their retirement account statement or plan portal.
There are several circumstances in which a participant may review or change a contribution election. The appropriate amount depends on the individual’s circumstances and the terms of the plan.
Changes in Compensation
A change in salary can affect the dollar amount contributed when contributions are based on a percentage of compensation.
For example, an employee contributing 8% of pay will generally have a different dollar contribution after a change in compensation, even if the contribution percentage remains unchanged.
A participant may therefore review the contribution election after a promotion, salary change, reduced work schedule, or other compensation change.
Changes in Household or Financial Circumstances
Major life events can change a person’s income, expenses, or financial priorities.
Examples may include:
These circumstances may lead a participant to review their existing payroll contribution election.
Approaching Retirement
Employees approaching retirement may also review their retirement-plan contributions and applicable contribution limits.
Eligible participants may have access to catch-up contributions if their plan permits them and they meet the applicable requirements. For 2026, the standard catch-up limit for many 401(k) plans is $8,000 for participants age 50 or older. A higher catch-up limit applies under certain rules to employees who are age 60, 61, 62, or 63 during the year.
Changes to the Employer’s Plan
An employer may modify its retirement plan’s provisions. Changes can affect contribution options, matching provisions, eligibility, or administrative procedures.
Participants should review communications from their employer and plan administrator when plan changes are announced.
For 2026, the employee elective-deferral limit for most traditional and safe-harbor 401(k) plans is $24,500. Participants who meet the applicable age requirements may also be eligible for catch-up contributions.
The standard 2026 catch-up contribution limit for many 401(k) plans is $8,000. Under SECURE 2.0 rules, participants who are age 60, 61, 62, or 63 during 2026 may have a higher catch-up limit of $11,250, subject to the applicable requirements.
These limits apply to employee elective deferrals and should not be confused with the separate overall annual-additions limit that can apply to total employer and employee contributions. For 2026, the defined-contribution annual-additions limit is generally $72,000, subject to applicable rules.
Participants should also remember that their individual plan may impose a lower contribution limit or other restrictions.
An excess deferral can occur when an individual’s elective deferrals exceed the applicable annual limit.
If this happens, the participant should contact the plan administrator. The IRS provides correction procedures for excess elective deferrals, including a general April 15 deadline for corrective distribution following the year in which the excess occurred.
The tax treatment of an excess deferral can depend on the circumstances, so participants should not assume that an excess amount will simply remain in the account without consequences.
Participants who contribute to more than one applicable retirement plan may also need to consider their combined elective deferrals when determining whether the annual limit has been exceeded.
It can, depending on the terms of the employer’s plan.
Some 401(k) plans provide employer matching contributions based on employee elective deferrals. The amount and conditions of any match are determined by the plan document.
For example, an employer may specify a particular matching formula or limit the portion of compensation eligible for matching contributions.
Because matching provisions vary, participants should review the plan’s matching formula before changing their contribution election.
Not necessarily.
A contribution election determines how much is directed from eligible compensation into the retirement plan. Investment elections are generally a separate part of plan administration.
A plan may allow participants to select from investment options offered under the plan. The available choices and procedures vary by plan.
Therefore, changing a contribution percentage does not automatically mean that a participant’s investment allocation will change.
A 401(k) contribution election may be adjustable during employment, but the specific rules are determined by the employer-sponsored plan.
Before changing a contribution amount, participants can review their plan documents, contribution limits, employer contribution provisions, and the effective date for changes. For questions involving an individual’s tax or financial circumstances, an appropriately qualified professional can provide guidance based on that person’s situation.
About State Employee Advisor Network: State Employee Advisor Network is a marketing and referral platform, not an investment adviser. The platform connects state and university employees with independent, licensed professionals. Any financial, investment, tax, or retirement guidance comes from the independent professional, not from State Employee Advisor Network.